
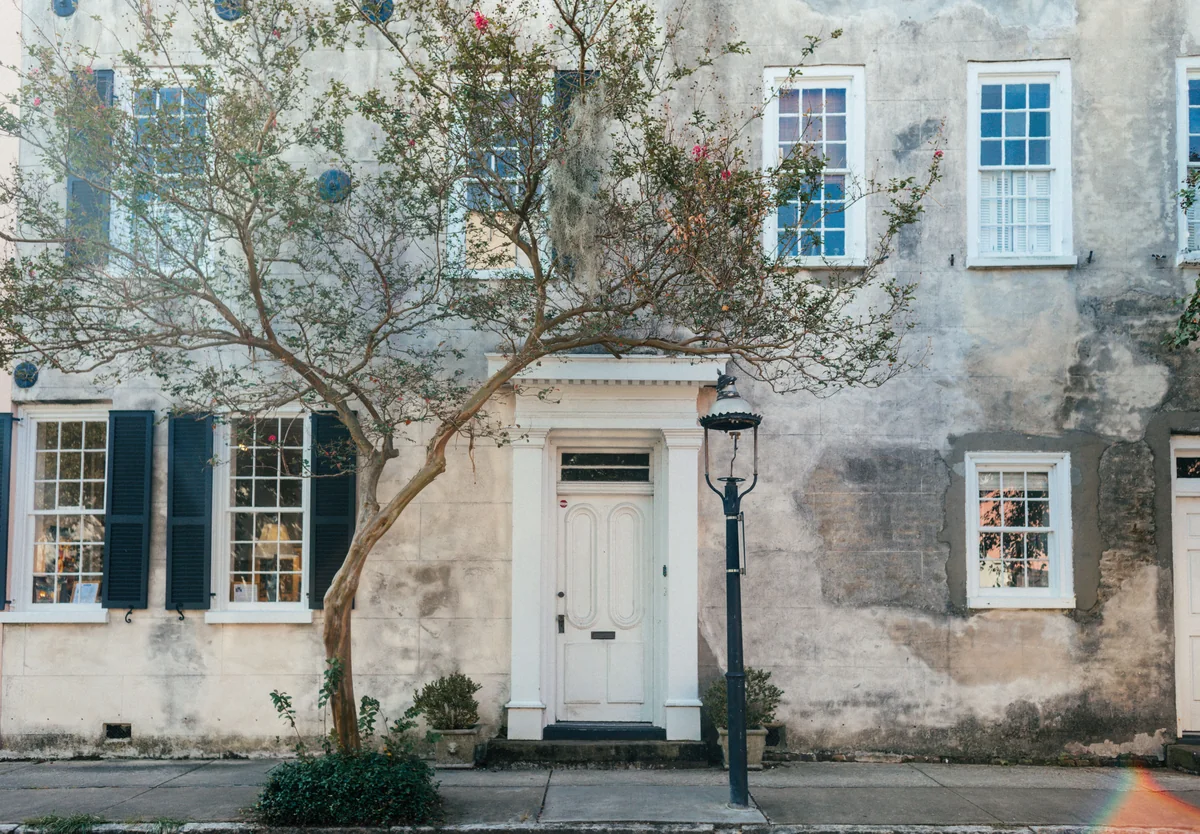
Separate rebuilding cost from market value
Market value reflects what a buyer may pay for the property, including its location and land. Rebuilding cost concerns the work and materials needed to reconstruct the insured structure on the policy's valuation basis. A mortgage balance and tax assessment serve still other purposes. None should be substituted automatically for the dwelling limit.
For a historic house, a basic square-foot estimate may miss plasterwork, custom millwork, masonry, special windows, decorative metalwork or a complex roof. For a newer high-value home, it may miss custom cabinetry, imported finishes, engineered systems or unusually large glazed areas. Give the estimator enough detail to identify the features that actually exist.
Ask how the estimate treats demolition, debris removal, access, labor and specialist work, and which expenses are instead addressed by separate coverage provisions. A rebuilding estimate is not a promise of claim payment. The policy's limits, exclusions, settlement basis and conditions still apply. Revisit the estimate after substantial renovations rather than assuming an annual automatic increase captures every change.
Identify preservation obligations before a loss
Determine whether the property is subject to a local historic district, an individual designation, a preservation easement or conditions connected to a rehabilitation program. These arrangements can impose different requirements. Do not assume every old home has the same restrictions, or that a listing on one register automatically establishes every local approval requirement.
The National Park Service's rehabilitation standards emphasize retaining historic character and distinctive materials within their applicable programs. The agency also explains that project-specific decisions benefit from qualified preservation professionals. Those standards are a useful planning resource, but they do not establish what a particular homeowners policy must pay or replace the local authority's determination.
Share relevant written requirements with your agent and rebuilding professional. Ask what would be required after partial damage, a major loss or demolition. If an easement or approval process could affect materials, design or timing, make that visible in the coverage review. A policy discussion is more useful when it addresses the property's actual obligations rather than the broad description “historic home.”
Read replacement-cost promises in context
Replacement cost, extended replacement cost, guaranteed replacement cost and functional replacement cost describe different concepts and can have insurer-specific conditions. Ask for the wording, not just a product label. Some provisions may depend on maintaining an agreed insurance amount, reporting improvements, completing repairs or rebuilding within a stated period.
Functional replacement may contemplate materials or methods that serve a similar purpose rather than reproduce every original feature. For an owner who expects historically faithful restoration, that distinction can matter. Discuss it directly and ask how a covered loss involving plaster, custom windows or antique flooring would be evaluated under the proposed form.
Do not assume that a high dwelling limit alone removes every limitation. Roof settlement, excluded materials, sublimits, matching issues and repair-time conditions may still apply. Ask the agent to explain where the policy addresses those questions. Keep a written summary of the accepted valuation basis and any unresolved limitations so the household understands the arrangement before a loss.
Review ordinance or law and partial-loss costs
After a covered loss, current building requirements can affect repairs even when parts of the structure remain undamaged. Ask whether the policy offers ordinance or law coverage and how it treats increased construction costs, demolition and undamaged portions. The available limit and triggering conditions matter; the presence of the phrase on a quote is not enough.
Distinguish general building-code requirements from preservation obligations, floodplain requirements and choices the homeowner makes voluntarily. A contractor may recommend improvements that are sensible but not automatically insured. Ask the relevant authority and qualified professionals what is actually required, then have the agent explain how the proposed policy responds.
For a South Carolina home in a flood-prone area, evaluate flood coverage and post-loss requirements separately. A homeowners ordinance endorsement should not be assumed to replace flood insurance or every flood-related compliance expense. Similarly, a separate wind policy may address certain costs differently from the main homeowners policy. Compare the complete arrangement rather than relying on one endorsement to solve every rebuilding problem.
Document updates without hiding original features
An older home may contain both carefully maintained historic materials and newer mechanical systems. Record the age and scope of roof, wiring, plumbing, heating and electrical-panel updates. A statement that the house was “fully renovated” is less useful than dates, permits where applicable, invoices and a clear description of what was replaced and what remains.
Disclose known issues and ongoing work. Outdated equipment, prior leaks, uncorrected damage or a partially completed renovation can affect underwriting. If the home will be vacant during a project, discuss the coverage needed for that period before work begins. A policy intended for an occupied residence may not fit the construction exposure.
Do not replace important original materials solely because an informal insurance comment suggests they are unacceptable. Obtain the specific insurer requirement and consult the relevant preservation or building professional where necessary. The objective is to reconcile a truthful insurance submission with the property's condition and obligations, not to promise an insurer will accept a feature before it has reviewed the facts.
Give coastal and inland hazards their own review
South Carolina historic and custom homes may face coastal wind and surge, inland flooding, severe storms and other property-specific hazards. A building's age or attractive location does not determine whether any of those risks is covered. Read the wind and hail terms, deductible triggers and flood exclusions separately.
If the main homeowners offer excludes wind, evaluate a separate wind policy and confirm where its coverage begins and ends. The South Carolina Wind and Hail Underwriting Association has limited geographic eligibility and specific requirements; it is not a statewide complete homeowners policy. A private market may also be considered when available. The precise address and construction details matter.
Flood and earthquake need separate evaluation because ordinary homeowners protection should not be assumed to include them. Ask about available endorsements or separate contracts, limits and deductibles. A lender's decision not to require a particular coverage is not proof that the hazard is absent. Our flood and earthquake guide explains the questions to ask without equating different causes of damage.
Inventory valuables and special property
A high dwelling limit does not automatically provide suitable limits for jewelry, fine art, antiques, collections or other valuable personal property. Policies can have category limits, special theft limits and differing settlement terms. Ask whether scheduled coverage or another arrangement is appropriate and what appraisals or documentation the insurer requires.
Create a room-by-room inventory with photographs, descriptions, receipts and relevant appraisals. Keep copies away from the home or in a secure digital location you can reach after a loss. For items whose value changes, ask how often updated information is needed. An insurance schedule and a tax or estate appraisal may serve different purposes.
Also identify property used for business, items in storage, collections displayed elsewhere and belongings owned by another person. Do not assume they are included because they are physically inside the dwelling. Ask about coverage during transit or restoration when relevant. The goal is to connect each important category with the actual policy provision rather than rely on a single broad contents figure.
Include the estate beyond the main house
List detached garages, guest cottages, workshops, pools, docks, retaining features and other structures for review. Their treatment may depend on use, construction and the cause of loss. A guest cottage rented to others can raise different issues from a storage building used only by the household. Avoid assuming that a percentage of the dwelling limit appropriately covers every detached building.
Describe household employees, home businesses, rentals, events and unusual amenities. Those facts can affect liability coverage and may require separate arrangements. An umbrella policy, if considered, has its own eligibility, underlying-insurance and exclusion requirements. Increasing a liability number on one policy does not establish protection for every activity.
For a home held in a trust or entity, coordinate ownership and insured status with the agent and appropriate advisers. Do not casually substitute an entity name on an application without considering the policy's definitions and permitted occupancy. Accurate ownership and use information helps the insurer evaluate the actual household and property interests.
Plan for a longer restoration process
Specialist labor, approvals and matching materials can complicate a restoration schedule. Ask how additional living expense coverage works after a covered loss, including the dollar limit, time limit and conditions. A generous building limit does not necessarily provide enough temporary housing support for a lengthy project.
If a home produces rental income, discuss the appropriate loss-of-rent coverage and its triggers instead of assuming an owner-occupied living-expense provision applies. If the property is a second home, clarify what additional costs would be eligible under the actual form. Different uses create different needs even when the buildings look similar.
Keep a contact list for the agent, insurer and qualified restoration professionals, but do not treat a contractor's estimate as an insurer's advance agreement to pay. After damage, follow the policy's notice and mitigation requirements, preserve documentation and coordinate major work with the claim process. Emergency protection and permanent restoration involve different decisions, particularly when historic materials may be affected.
Build a property file that supports a meaningful comparison
A useful submission includes current photographs, a feature description, recent rebuilding estimate, system-update dates, loss history, occupancy and ownership information, and relevant preservation documents. Identify custom and historic details that a standard form might miss. The quality of this information can matter more than a broad label such as luxury, landmark or estate.
Hypothetical example: two homes have the same size, but one has standard finishes and the other has original plaster, custom windows and detailed masonry. Giving both the same rebuilding assumptions may overlook meaningful differences. A specialist review can identify those differences, while the insurance comparison determines which costs are covered under each proposed contract.
Compare offers by insurer, valuation basis, limits, endorsements, deductibles and total cost. Ask what remains excluded and what further information is required before binding. A careful review cannot eliminate every risk, but it can make the chosen arrangement understandable and better aligned with the home you would actually need to repair or rebuild.
Before accepting the offer, ask who will handle inspection follow-up and whether any recommendations carry a completion deadline. Keep the inspection report with the property file and document accepted corrections. If a proposed recommendation conflicts with a preservation obligation, raise that conflict promptly with the insurer and the appropriate professional. Do not assume either requirement can be ignored. Clarifying expectations early makes it easier to choose a workable policy and plan necessary maintenance without creating an avoidable disagreement after the contract begins.
Frequently asked questions
Should I insure a historic home for its sale price?
Do not assume sale price is the right dwelling limit. Land, location and market demand differ from rebuilding costs. Use an estimate that reflects the actual structure, materials and the policy’s valuation basis.
Does historic designation guarantee restoration coverage?
No. A designation or preservation requirement does not rewrite an insurance contract. Identify the property’s actual obligations and compare them with the policy’s settlement terms, limits, exclusions and ordinance coverage.
What is functional replacement cost?
The concept may allow repair or replacement using materials or methods that perform a similar function rather than reproduce every original feature. Read the specific wording and discuss whether that basis fits your restoration expectations.
Will a large contents limit protect all jewelry and antiques?
Not necessarily. Special categories can have sublimits and different settlement terms. Ask about scheduled coverage, appraisals and documentation for important items instead of relying only on the overall contents amount.
Can surplus insurance cover a historic or custom home?
An eligible surplus lines insurer may consider a property that does not fit another market, subject to underwriting and terms. Admitted specialty options may also exist. Neither market label alone establishes the breadth of restoration coverage.
What should I provide for a quote?
Supply photos, construction and finish details, system-update dates, rebuilding information, claims, actual use, ownership and relevant preservation requirements. Accurate documentation helps the agent seek terms that address the property’s distinctive features.
Sources and further reading
Read the underlying guidance and your actual policy together. Source dates and scope matter; the policy and applicable law control.
- South Carolina Department of Insurance: Types of Coverage
- South Carolina Department of Insurance: Additional Homeowners Insurance Coverage
- South Carolina Department of Insurance: Homeowner's Insurance
- National Park Service: Secretary of the Interior’s Standards for Rehabilitation
- South Carolina Wind and Hail Underwriting Association: About Us
Prepared for South Carolina Surplus. How we prepare these guides.